IASbaba’s Daily Current Affairs – 22nd September, 2015
BASEL III norms and INDIA
Terms
Explanation
Bank’s capital:
Bank’s own money (apart from Liability + Asset)
Tier 1 capital:
Most Liquid Capital with bank
Can be sold easily to ward off Crisis
Eg: Common Shares + Preferential Shares
Tier 2 capital:
Not as liquid as Tier-I
Eg: Debts (bonds) + Hybrid instruments (Having both characteristics of Debt and Equity)
Tier 3 capital:
Least Liquidity
Capital adequacy requirements (CAR)
Ratio of a Bank’s Capital to its Risk (absorb a reasonable amount of loss)
Higher CAR à More stability
Therefore,
Basel Capital adequacy requirement (CAR)
= 9% of RWA (Risk weighted assets)
OR
BASEL CAR:
[7% of RWA in T1] + [2% of RWA in T2]
Risk Weighted Assets (RWA)
Home Loan
20% Riskà
Loaned: 30 Crores
Vehicle Loan
30% Riskà
Loaned: 20 Crores
Commercial Loan
50% Riskà
Loaned: 50 Crores
Risk Weighted Assets
100%
100 Crores
Have 9 Crore as TOTAL CAPITAL ADEQUACY if you want to loan out 100 crore
Basel I
Criticisms:
Rigidity of “one-size fits” approach
Absence of risk sensitivity in estimating capital requirements
Basel II:
Banks had to maintain the minimum capital requirement of 8% against the risk weighted assets
Computation of RWA based on ‘three’ Risks:
Credit,
Market, and
Operational Risks
Three Pillars:
Minimum capital requirements,
Supervisory review process, and
Market discipline
Criticisms:
Failure to address a number of issues during the Financial Crisis (2007–08)
Pro-Cyclical: In better times, it didn’t impose additional capital requirement on banks but during the crisis, looked out for banks bringing in more of Capital. It was this failure to add in additional capital that led to hurting the financial system, plunging in deep into Recession.
Absence of Regulation Governing Leverage: The assumption that the risk based capital requirement would in itself mitigate the risks of excessive leverage became a cause of the crisis.
Did not consider liquidity risk as part of capital regulation and this led on to a Solvency Risk
More focus on the individual financial institutions, ignoring the risks arising from the interconnectedness across institutions and markets leading the crisis to spread across various financial markets.
Basel III: A Global Regulatory Framework for more Resilient Banks and Banking systems
Objectives:
To strengthen global capital and liquidity regulations with the goal of promoting a more resilient banking sector
To improve the banking sector’s ability to absorb shocks arising from financial and economic stress.
Enhancements:
Augmentation in the level and quality of capital
Introduction of liquidity standards
Modifications in provisioning norms
Introduction of leverage ratio
Pillars:
Minimum Regulatory Capital Requirement based on Risk weighted assets
Maintaining capital (Credit, market and Operational Risk)
Supervisory Review Process
Regulatory Tools and Frameworks to deal with risks
Market Discipline
Transparency of Banks
India:
Minimum capital requirement in India is higher at 9% of the risk-weighted assets
All commercial banks – Regional rural banks
Commercial banksà approximately 87% of total banking system assets
Public sector banks: Market share of 73% banking assets and 82% of bank branches
Foreign banksà 6% of the Indian banking sector
Issues with Indian Banks:
Profitability
Capital acquisition
Liquidity Needs
Limits on lending: ‘Urgent need to take control of bad loans (NPAs) + selection of borrowers based on proper due diligence and not on relationships’
Bank consolidation: ‘Consolidate weaker banks with stronger ones and this would attract more funding from both international and local capital markets’
Pressure on Yield on Assets
Pressure on Return on Equity: ‘Will face decline in the short run’
Stability in the Banking system:
‘The need for banks to ensure that the de-recognised portion of existing additional Tier I and II capital is replaced with Basel III complaint capital leads to the balance sheet not being static and therefore there is a need to step up the capital to address this.’
RoE: Return on equity measures a corporation’s profitability by revealing how much profit a company generates with the money shareholders have invested.
Current Scenario:
Budget 2014: Banks themselves will have to raise money by selling shares to public, in a phase manner but Government will continue to remain the majority shareholder.
India remains “Compliant” with the Basel III global regulatory framework for implementing risk-based capital requirements
An overarching issue regarding the use of the word “may” in India’s regulatory documents for implementing binding minimum requirements; but RBI has maintained its usage explaining that it is binding on the Banks.
There still remains distance to be covered in complying with the standards for liquidity coverage ratio (LCR), or highly liquid assets held by banks to meet their short-term obligations.
Criticisms:
There exists tools like CRR + SLR + Regular Reporting to RBI as a sufficient “backup” mechanisms to prevent banking crisis in India
The approach of one-size-fits-all shouldn’t be applied. It restricts the flow of money in the economy of a developing country where it can be provided to those who really need it.
Connecting the Dots:
Examine how the Basel-III mechanism plans to correct the wrongs done by Basel-II?
Is India capable enough to prevent a banking crisis? Critically analyse the issues faced by the Banking sector w.r.t the Basel-III norms.
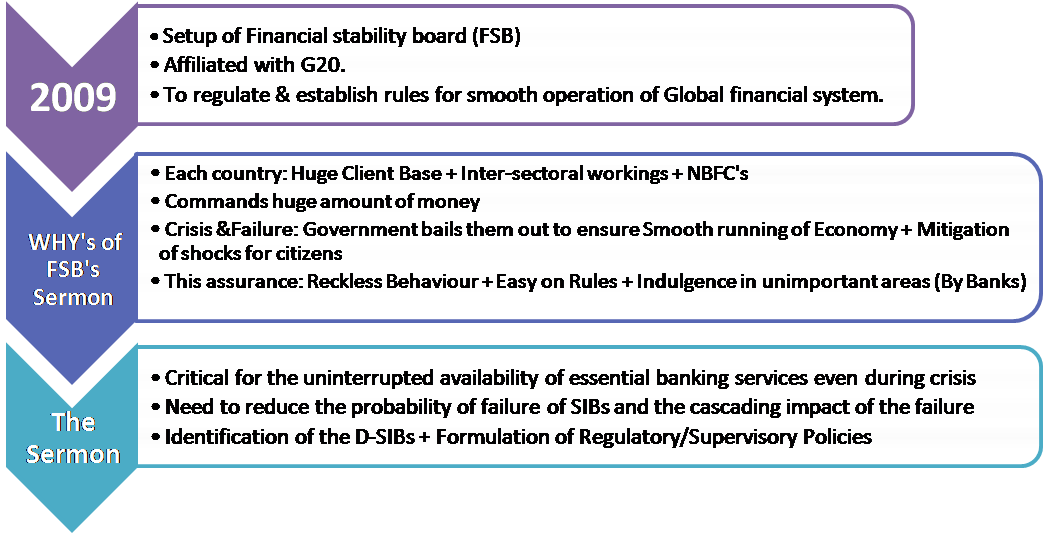
D-SIB: Domestic Systemically Important Banks: Too Big to Fail?
Types of SIB’s
Global Systematically Important Bank (G-SIB)
Too important to fail all over the world
By BASEL Committee on Banking Supervision
Domestic Systemically Important Banks (D-SIB)
Country’s Central Bank identifies + decides the parameters to be complied
India’s RBI: A Cautious Beginning
ICICI and SBI:
Combined Assets: Over one-fifth of the country’s GDP
Strong Capital Adequacy Ratio (CAR)
Risk of operations: Risks emanating from the Quality of Borrowers
Huge divergence in Size + Nature of Operations
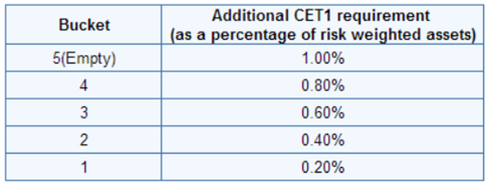
Capital fixed at a lower point–>0.2 per cent to 0.8 per cent extra capital, based on the category under which they fall
Indicators used:
Size: Loans + Savings Deposits, etc
Interconnectedness: With different Financial Institutions
Substitutability: Services can be substituted or are replaceable
Complexity: Higher Complexity–>More Time + Expenses to resolve disputes/issues
Weak Credit growth + Rising Bad Loan + NPA’s–>Should not over-burden Banks (less number of Bank designated as D-SIB this year)
Foreign bank in India(Global Systemically Important Bank)
Branch presence in India
Need to maintain additional CET1 capital surcharge in India (as applicable on it as G-SIB), proportionate to its Risk Weighted Assets in India
Benefits
Stringent Supervision + Strict Regulation of Rules
Behaviour Management: Efficient Working + No crisis
Additional Capital: Will act as a Shock Absorber
Tax-payer’s Money: Proper Utilization in providing services to the taxpayers
Limitations
No stringent control over NBFC’s
Why?
NBFC’s: In the ‘shadow’ of the main banks
Carry bank like operations
But not subject to Regulations
RBI guidelines but not up-to-the-mark
FSLRC Report by Justice BN Srikrishna
Creation of new Single Statutory Bodies for proper Accountability + Supervision
Inclusion of less number of Banks
Additional Capital to be maintained is very less; might amount to less strictness and a lethargic mind-set à Bad for the future
Reforms to revive some PSB’s: Too slow; Leads to leaving out of a huge amount of earnings and the scope of capital that it can raiseà Hasten the process!
Connecting the Dots:
What do you mean by Shadow Banks? What are the reforms suggested by Justice BN Srikrishna’s report for Financial Sector Legislative Reforms (FSLRC)?
Examine the reasons plaguing the revival of some of our PSB’s. Suggest a way ahead.